What Does a Corporate Tax Return Extension in Indonesia Involve?
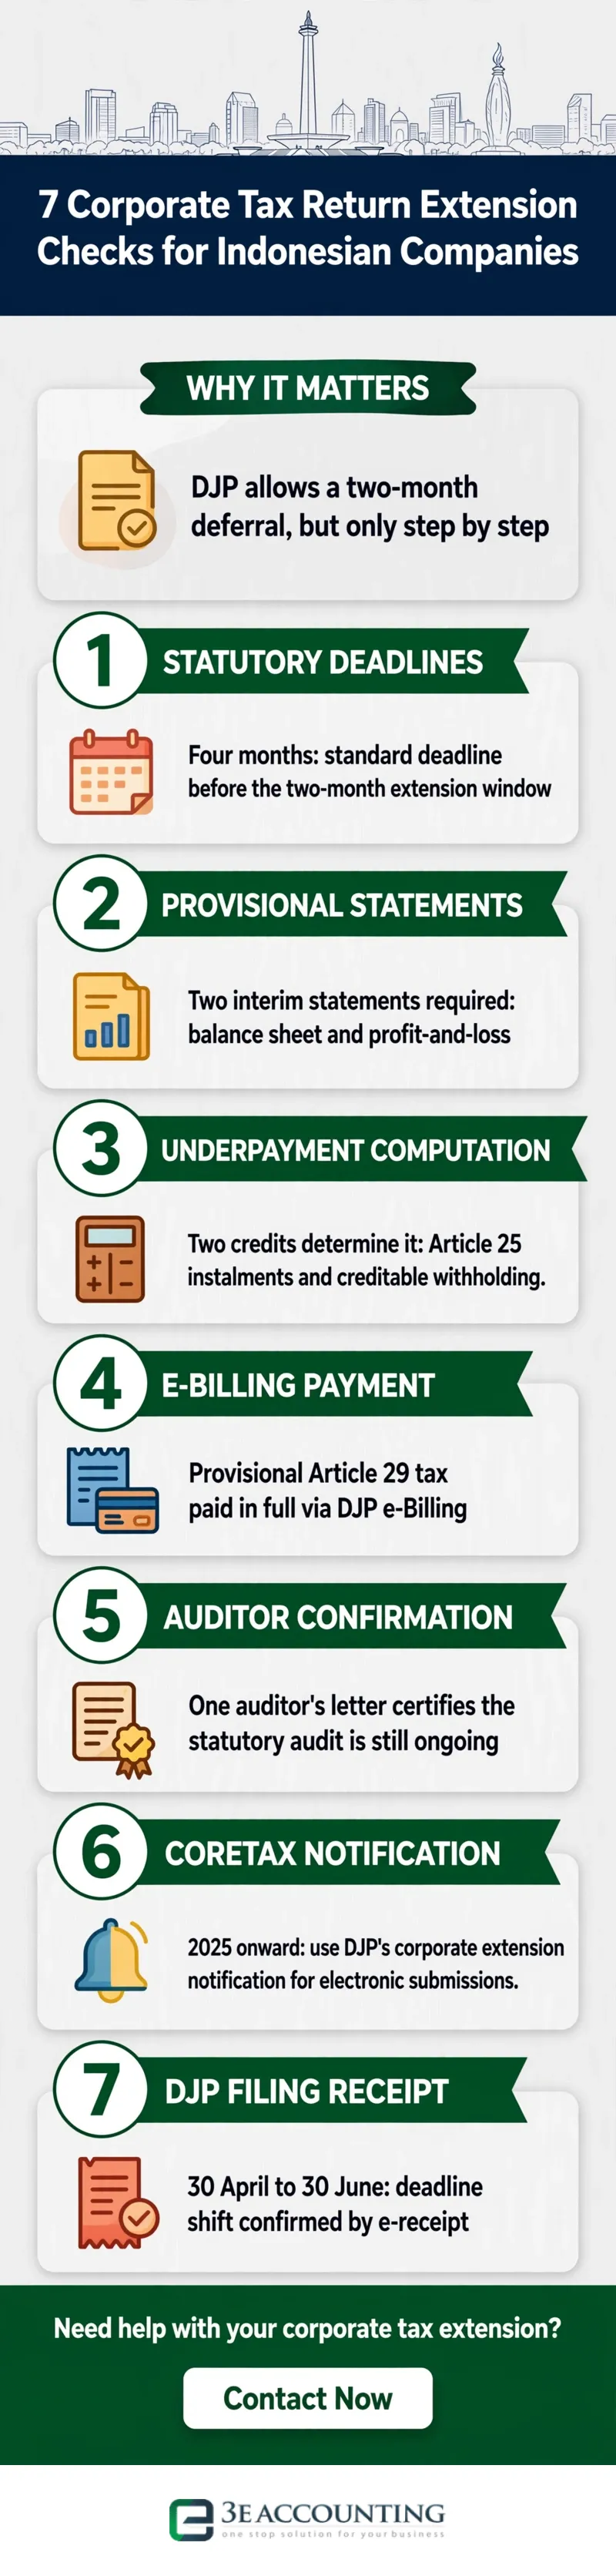
Indonesia's Directorate General of Taxes (DJP) gives companies four months after the fiscal year-end to file their annual corporate income tax return. When that window proves too tight, a corporate tax return extension in Indonesia can add up to two further months. It requires a formal, correctly sequenced process. The company must notify DJP and attach provisional financial statements and a provisional tax calculation. It must also settle any provisional Article 29 underpayment before filing. An incomplete notification can be rejected, leaving the company exposed to late-filing sanctions. In this infographic guide, we set out seven compliance checks for requesting a deferral. They cover statutory deadlines through to the electronic filing receipt.
What Are the Corporate Tax Filing Deadlines and Extension Checks?
Indonesia's corporate tax return falls due four months after the fiscal year-end, 30 April for calendar-year companies. DJP allows eligible taxpayers an extension of up to two months, requested before the original deadline passes. Confirm the company's tax identification number (NPWP) is active. Check its company registration number (NIB) for consistency, although DJP does not list it as an extension requirement. Under Article 7 of the tax administration law, a late corporate return can attract a Rp 1,000,000 administrative penalty.
How Do You Prepare Provisional Statements?
Two key components of the provisional statements are an interim balance sheet and a profit-and-loss statement. DJP requires these provisional financial statements for the relevant tax year as mandatory attachments to the notification form. Draft them from the closed ledgers so the figures reconcile with the monthly Article 25 instalments already reported. Incomplete statements can cause DJP to reject the notification. If the return is then filed after the original deadline, late-filing sanctions may apply.
How Do You Compute the Article 29 Underpayment?
Two tax credits help determine any provisional Article 29 underpayment: Article 25 instalments and creditable withholding. Subtract these credits from the provisional annual liability shown in your interim statements. This kurang bayar figure is the provisional settlement required for the extension application. If the provisional amount is later found to be lower than the final corporate income tax due, interest applies on the shortfall from the original payment due date until the difference is paid, and the application may be rejected.
Settle Tax via e-Billing
If there is a provisional Article 29 underpayment, generate a billing code in Coretax DJP and pay before filing. Keep the resulting state revenue receipt (BPN) as proof of settlement. DJP treats the payment date as decisive: the underpayment must clear on or before the original filing deadline. Archive the BPN with the dossier; proof of payment is required when there is an underpayment.
Corporate tax return extension at a glance
| Check | Summary |
|---|---|
| Original filing deadline | Four months after fiscal year-end; 30 April for calendar-year companies |
| Maximum extension | Two months beyond the original deadline |
| Provisional underpayment | Pay any amount due before filing the notification |
| Late-filing penalty | Rp 1,000,000 for a corporate annual return |
Obtain Auditor Confirmation
One public accountant's statement is required if the financial statements are being audited and the audit is unfinished. Attach it to the Coretax extension notification. The statement confirms that the audit is still in progress. Arrange it early, because the practitioner cannot certify audit work that has not yet begun.
Complete the Coretax Notification
2025 and later tax years use Coretax DJP's corporate extension notification for electronic submissions. Complete every field: the NPWP, the tax year, the reasons the return will be late, and the provisional Article 29 amount already settled. The company representative or authorised agent must sign; an agent must provide a special power of attorney. If the financial statements are being audited and the audit is unfinished, attach the public accountant's statement before submission; DJP then reviews the notification and confirms whether it is accepted.
Track the DJP Receipt
An accepted maximum extension shifts the deadline from 30 April to 30 June for calendar-year companies. For tax years from 2025, submit the dossier through Coretax DJP rather than DJP Online. Download the electronic receipt as proof of submission and check DJP's decision on the notification. Check the applicable Indonesia time zone before any midnight cut-off, and diarise the extended corporate tax deadline immediately.
Need Help Extending Your Corporate Tax Deadline?
We handle extension notifications, provisional Article 29 computations and Coretax DJP submission to help you meet the requirements.
Frequently Asked Questions
Up to two months beyond the original four-month deadline. For calendar-year companies, an accepted maximum extension moves the filing deadline from 30 April to 30 June.
For tax years from 2025, companies can submit the extension notification through Coretax DJP. It includes the tax year, the reason for the delay and provisional tax figures.
Yes. Any provisional Article 29 underpayment must be settled before filing the notification. Include the state revenue receipt (BPN) as proof of payment.
The return counts as late. Under Article 7 of the tax administration law, a late corporate annual return can attract a Rp 1,000,000 administrative penalty.
The electronic receipt is proof of submission. Keep it and check DJP's decision to confirm whether the extension notification was accepted.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.