What Goes Into an Indonesian Monthly VAT Return?
Every month, Taxable Entrepreneurs (Pengusaha Kena Pajak, PKP) in Indonesia file one statutory return, the SPT Masa PPN; the legacy version was SPT Masa PPN 1111. This Indonesian monthly VAT return reconciles output tax charged on sales against input tax paid on purchases.
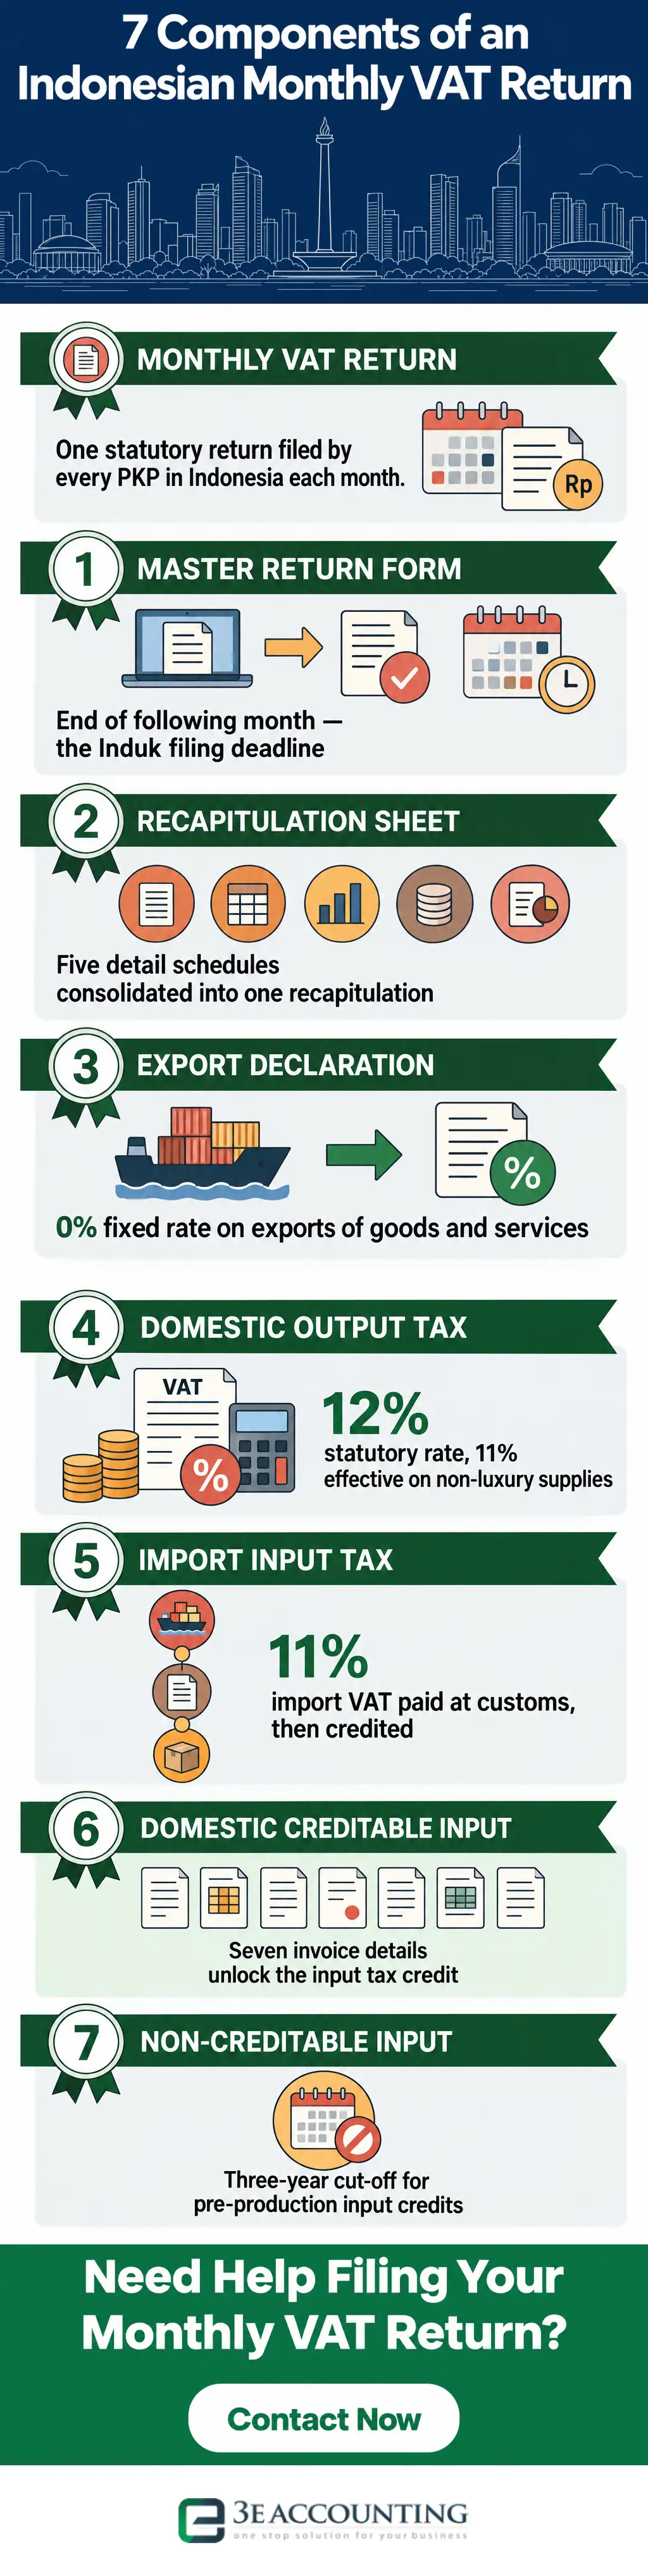
In this infographic, we break down the seven components of the legacy Form 1111 used by PKPs not using the input-tax crediting guideline, and note where the current Coretax return differs.
Registration is compulsory once taxable deliveries exceed IDR 4.8 billion in a fiscal year. The Directorate General of Taxes (DGT) e-Faktur platform supports tax invoice preparation, and PKPs can also use Coretax DJP to prepare invoices and submit returns. In 2026, the statutory VAT rate is 12%, applied as an effective 11% on non-luxury supplies. The legacy return spans one master form and six attachment schedules. Each component carries a distinct reporting scope, and errors flow straight into the net position. Our corporate tax planning and tax advisory team prepares and reviews these filings for clients across Indonesia.
What Is the Form 1111 Master Return Form?
According to the DGT, the VAT return must be filed by the end of the month following each tax period. The Induk serves as the executive summary, converting attachment totals into one net position. It consolidates output VAT against creditable input VAT to show an underpayment or overpayment.
Where input exceeds output, the form carries the refund or carry-forward election. Any shortfall must be paid before the return is submitted.
What Is the Form 1111 AB Recapitulation Sheet?
5 detail schedules were consolidated in legacy Form 1111 AB, according to the DGT. It aggregated taxable supplies from 1111 A1 and A2, alongside input tax from 1111 B1, B2, and B3. The consolidated tax base (Dasar Pengenaan Pajak, DPP) and VAT totals then fed into the Induk's net calculation.
The current Coretax return uses a redesigned structure, so taxpayers should check the applicable fields and reconcile each figure before submission.
What Is the Form 1111 A1 Export Declaration?
Qualifying exports of taxable goods and services carry a 0% VAT rate. Schedule 1111 A1 captures every qualifying transaction, spanning tangible goods, intangible goods, and taxable services delivered to overseas customers.
According to the DGT, tangible-goods exports generally require customs export documentation. Eligible service and intangible-goods exports instead require an export notification with an invoice; zero-rating on services is subject to statutory limitations. Correctly declared exports keep the supply chain competitive while preserving the full input tax credit.
Form 1111 A2 Domestic Output Tax
Indonesia's standard VAT rate is 12% in 2026, charged as an effective 11% on non-luxury supplies. Schedule 1111 A2 reports output VAT on every tax invoice issued to domestic buyers for deliveries within the Indonesian customs area.
The 11% effective rate flows from a tax base set at 11/12 of the sale value. Only luxury goods attract the full 12%. Accurate A2 totals underpin the entire input-output reconciliation.
Legacy Form 1111 components at a glance
| Component | Reporting scope |
|---|---|
| Induk | Master return and net VAT position |
| 1111 AB | Recapitulation of supplies and input tax |
| 1111 A1 | Qualifying exports |
| 1111 A2 | Domestic output tax |
| 1111 B1 | Creditable input tax on imports |
| 1111 B2 | Creditable domestic input tax |
| 1111 B3 | Non-creditable input tax and facilities |
Form 1111 B1 Import Input Tax
Imported goods attract the standard VAT rate, an effective 11% on non-luxury items in 2026, collected at customs clearance. Schedule 1111 B1 records this input VAT for credit against output tax in the same monthly cycle.
Imported-goods entries must be supported by the applicable import declaration and official tax payment evidence. B1 also covers creditable VAT on services and intangible goods used in Indonesia from outside the customs area, supported by an official tax payment slip. Careful B1 reporting turns a border cash cost into recoverable tax.
Form 1111 B2 Domestic Creditable Input
7 minimum details must appear on a tax invoice before input VAT becomes creditable. The required fields range from the supplier's name and tax identity to the invoice's serial code and issue date.
Schedule 1111 B2 lists creditable domestic invoices from local vendors covering purchases, operating expenses, and business overheads. Credits are generally claimed in the same tax period, subject to a three-month window where the applicable conditions are met and the amount has not been expensed or capitalised.
Form 1111 B3 Non-Creditable Input
3 years after input VAT is first credited, pre-production credits can become non-creditable if no related taxable supply or export has been made; certain sectors may have longer periods.
Schedule 1111 B3 reports input VAT that cannot be credited for statutory reasons or purchases covered by government-borne VAT facilities. Typical cases include purchases supporting exempt deliveries, non-business use, and invoices that fail the validity tests. Reporting these amounts keeps each monthly VAT return honest and audit-ready.
Need Help Filing Your Monthly VAT Return?
Our corporate tax planning team prepares and reviews monthly VAT returns through Coretax for businesses across Indonesia.
Frequently Asked Questions
The current monthly VAT return must be filed by the end of the month following the tax period, and any net VAT shortfall must be paid before submission.
The legacy Form 1111 had seven parts: the Induk master form plus schedules 1111 A1, A2, AB, B1, B2, and B3. The current standard return lists Induk, A1, A2, B1, B2, B3, and C; requirements differ for some taxpayers.
The statutory rate is 12%, applied as an effective 11% on non-luxury goods and services through the DPP 11/12 adjustment; qualifying exports are zero-rated.
Entrepreneurs whose taxable deliveries exceed IDR 4.8 billion in a fiscal year must register as PKPs and file returns through Coretax DJP.
Yes. Input VAT reported in schedule 1111 B1 is creditable subject to the applicable crediting conditions and supporting documentation, including an import declaration and tax payment evidence where required.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.